🏠 When Did Buying a House Start Feeling Like a Bigger Grift Than Dealer Fees?
🏠 REAL-WORLD CONVERSATION
I was talking with a friend of mine about the real estate market right now.
- War headlines everywhere.
- Gas prices creeping back up again.
- People all over social media losing their minds.
And somewhere in that conversation I thought:
I should probably write a listing about this on Housing Freak.
Not political.
Not dramatic.
Just a real-world observation:
👉 Something feels off.
Like we’re slowly warming up for:
🎬 The Big Short 2
And this time?
It won’t be explained on CNBC…
👉 it’ll be on your teenager’s TikTok feed
👉 with a 22-year-old explaining seller financing in 30 seconds
💰 LET’S JUST WALK THROUGH IT
Let’s take a completely normal house:
👉 $550,000
Nothing crazy.
That’s just… housing now.
FHA Buyer
• $16,500 down
• ~$15,000 closing costs
👉 $31,500 just to get in the door
Conventional Buyer
• $27,500 down
• ~$15,000 closing
👉 $42,500 upfront
VA Loan (The “Zero Down” Story)
Sounds great.
Until you realize:
👉 ~$18,150 funding fee
👉 (just rolled into the loan so it doesn’t sting upfront)
🤔 WAIT… WHEN DID THIS BECOME NORMAL?
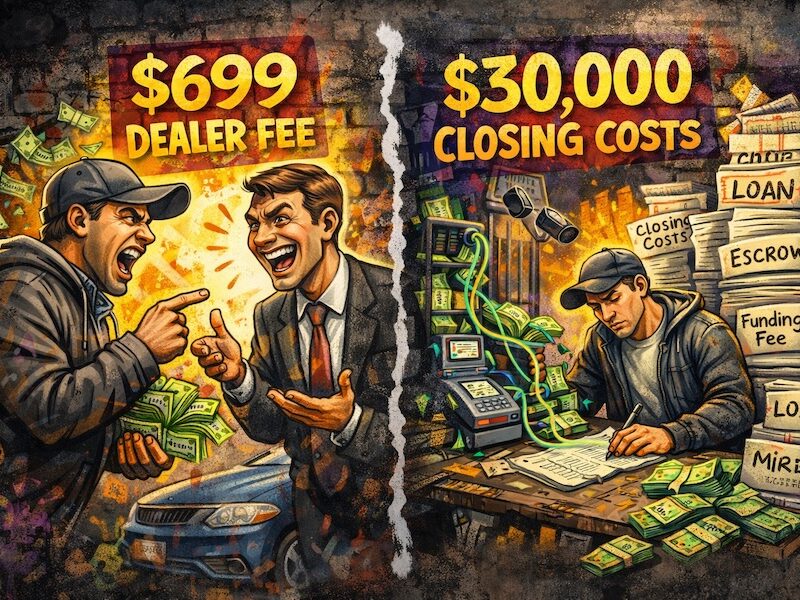
People will absolutely lose their minds over:
👉 a $699 dealer fee
They’ll argue.
Walk out.
Leave reviews.
But in housing?
👉 $30,000–$40,000 disappears at closing…
…and everyone just signs like it’s part of the experience as they grab the new garage keypad code and wait for a cheap housewarming gift to show up.
We’re talking about handing over what amounts to a year’s salary for many people…
just to get access to the “American Dream”
and start making payments for the next 30 years.
“Guido-style” car loans at 18% for six years suddenly start looking like a deal compared to this.
👉 This might be one of the most expensive “normal” transactions people accept without ever questioning it.
💸 THEN COMES THE PART THAT REALLY HITS
At ~6.25%:
👉 ~$4,250/month
And not long ago?
👉 ~5.75%
That little shift?
👉 Costs thousands more
👉 Reduces buying power
👉 Tightens qualification
👉 Has people draining savings accounts and rethinking every other plan they had.
“We’ll take that trip to Disneyland next year kids.”
💥 AND HERE’S WHERE IT GETS WEIRD
You don’t just pay all of that.
👉 You still have to qualify.
- Income
- Credit
- Debt ratios
- Documentation
You might not even get approved unless they decide you’re “worthy”…
…to borrow money and pay roughly double for the property over time.
So let me get this straight:
You bring $30,000+ to the table…
👉 and still have to ask permission?
That’s when it really clicked.
👉 This isn’t just expensive
👉 It’s structured
🏛️ WE’VE SEEN THIS MOVIE BEFORE
After everything exposed in
🎬 The Big Short
After regulations…
After oversight…
After everything was supposedly “fixed”…
Why does it still feel like:
👉 the system extracts maximum value at the point of entry?
Honestly?
It felt less broken in 2008 than what’s happening now.
⚖️ SO WHAT HAPPENS NEXT?
When systems get expensive…
👉 people don’t just accept it
👉 they start routing around it
🔄 Seller Financing (Quiet Comeback)
- Flexible terms
- Less friction
- Different structure
And here’s the reality:
You’re about to start seeing this everywhere.
Not on late-night TV.
👉 On TikTok
👉 On Instagram
👉 On YouTube Shorts
Because when the math breaks…
👉 the message spreads fast
And that’s when the real estate gurus reappear…
👉 like they just discovered seller financing yesterday.
🚀 BUT HERE’S THE PART MOST PEOPLE MISS
Everyone focuses on:
👉 “How do I buy the house?”
Almost nobody asks:
👉 “How do I offset it?”
That’s where things get interesting.
💡 THE DIFFERENT WAY TO LOOK AT THIS
This listing you’re reading right now?
It’s not a blog post.
It’s not a rant.
Well… it’s kind of a rant — that’s my trademark.
👉 But it’s still a listing.
And that’s the whole point.
Instead of just:
• reading
• scrolling
• consuming
You can:
👉 create one
👉 share it
👉 build around it
👉 even edit it after you test the response
⚙️ HOW THIS TURNS INTO MONEY (NO FLUFF VERSION)
You join Housing Freak.
(It’s free.)
You get a link.
Now you’re an affiliate.
And affiliate marketing isn’t new…
👉 Bezos built Amazon on it.
You send someone a listing like this and say:
👉 “You should create one like this.”
They join for $49.95
👉 You earn ~30% (~$15)
That’s it.
No product
No inventory
No ads
🎥 REALITY CHECK: PEOPLE ARE ALREADY DOING THIS… JUST IN THE WRONG PLACE
I just dropped a YouTube video into this listing.
At the time I added it to the bottom of this listing the guy has:
👉 26 views
👉 13 subscribers
👉 Solid content
And he’ll probably make:
👉 $0
That’s not a knock.
That’s the system.
The same way this housing system works…
👉 taking more money, faster, than Robert De Niro running a table in Casino.
Because on YouTube:
👉 You need thousands of subscribers
👉 Thousands of watch hours
👉 Algorithm luck
Before you ever see a dollar.
But here?
👉 One person clicks
👉 One person creates a listing
👉 You get paid
Same effort.
Completely different outcome.
👉 This is basically YouTube…
👉 except you don’t need 10,000 subscribers to make $15
And here’s the part that really doesn’t make sense…
People will spend YEARS:
👉 trying to get 1,000 subscribers
👉 trying to monetize content
👉 hoping something “hits”
But won’t spend:
👉 30 minutes creating something like this
👉 and actually attaching a way to get paid
That’s not a tech problem.
👉 That’s a mindset problem.
People aren’t confused.
They’re just stuck in the wrong system.
💥 REAL EXAMPLE (THIS ONE SHOULD WAKE YOU UP)
One of my listings on Travelers Freak:
👉 600+ views
👉 No ads
👉 Just shared the link
Same idea.
Same effort.
But here’s the difference:
👉 That listing is positioned to actually make money
👉 The YouTube video isn’t
That’s the gap.
🔁 NOW IMAGINE THIS
Do that 100 times:
👉 ~$1,500
If 30 people do the same:
👉 ~$15,000
Next layer?
👉 ~$225,000 potential
Not magic.
👉 Distribution + repetition + commissions
🧓 WAIT… AREN’T ANNUITIES JUST FOR GRANDPA?
You know…
👉 Monthly check
👉 “Second Social Security”
👉 Set it and forget it
Yeah — that’s what most people think.
That’s not what I’m talking about.
I’m talking about:
👉 using predictable income
👉 as a housing pressure offset
Not a retirement pitch.
Not a product debate.
Just structure.
Because here’s the truth:
Owning a house with:
❌ unpredictable income
❌ no income floor
That’s where people get into trouble.
Not when they buy.
👉 Years later.
That’s what this framework is about:
👉 Income behaving like rent
👉 Supporting ownership
👉 Stabilizing long-term pressure
If you want to see that angle:
👉 https://salesfreak.com/the-sales-freaks-annuity-in-a-box/
🤔 HONEST QUESTION
You just read this entire listing.
You’ve probably:
👉 watched videos like this
👉 read posts like this
👉 thought about this before
So here’s the real question:
Why aren’t you doing this?
Not buying a house.
👉 Creating something like this
Because this right here:
👉 is a listing
👉 with a story
👉 with a link
👉 that can earn money
And it took:
👉 one idea
👉 a little AI help
👉 about 20–30 minutes
Meanwhile…
People spend YEARS:
👉 trying to grow YouTube
👉 chasing algorithms
👉 waiting for something to hit
When they could just:
👉 create
👉 share
👉 repeat
That’s it.
📣 THE MOVE
Most people will scroll past this.
A few will try it.
👉 Those are the ones this works for.
- Create a listing.
- Tell the story.
- Break something down.
Because when you turn a transaction into a story…
👉 it becomes an asset
🔥 FINAL THOUGHT
You don’t need to beat the system.
👉 You just need to stop showing up to it the same way.
If this made you think for even a second…
👉 you’re already ahead of most people.